Putnam US Value Equity
Mandate commentary
Q3 2026
Highlights
① In a modestly positive environment for U.S. stocks, the portfolio outperformed its benchmark, the Russell 1000 Value Index.
② Earnings growth provided a powerful tailwind for equities.
③ Inflation, energy costs pushed long-term yields higher.
Mandate overview
 For the quarter, U.S. equities, as measured by the S&P 500 Index, returned 2.3%. In early August, the S&P 500 reached new highs, supported by strong corporate earnings and a rebound in technology shares. Late in the month, the focus shifted to inflation and interest rates. Renewed attacks on oil facilities in the Middle East pushed oil prices higher, and a stronger-than-expected jobs report added to expectations for tighter policy. On September 16, the U.S. Federal Reserve raised interest rates by 25 basis points and signaled at least one more hike by year-end. Throughout the month, investor sentiment shifted between concern over rising yields and oil prices and optimism about technology earnings, which continued to support the market.
During the period, the portfolio outperformed the benchmark. Both security selection and sector allocation decisions contributed to relative performance.
Stock selection impacts were most positive in the energy, information technology and consumer staples sectors, partially offset by weakness in industrials, utilities and financials. From a sector allocation perspective, performance benefited most from overweight exposure to information technology and energy, and underweight exposure to industrials.
Mandate: US Large Cap Value Concentrated SMA
Performance contributors
Microsoft – The overweight position was a top contributor, as investors became more confident in the company’s ability to capitalize on its AI investments.
Valero Energy – An overweight was a positive contributor, as the conflict in the Middle East drove an increase in crude oil prices and refining margins.
Thermo Fisher Scientific – An overweight was a positive contributor after the company reported strong fundamental results for the second quarter.
Performance detractors
NRG Energy – An out-of-benchmark position was the largest relative detractor. Investor enthusiasm declined amid political pressure and power contracts that have been slow to secure.
Southwest Airlines – The portfolio’s overweight position had a negative impact. Broadly, airline profitability has been challenged by increasing jet fuel costs.
Citigroup – A relative overweight weighed on results. While the company reported strong results, it forecasted an increase in operating expenses.
Total gross returns:
Total return (USD) | QTD | YTD | 1YR | 3YR | 5YR | since INC. (NOV. 14, 2016) |
PUTNAM US VALUE EQUITY | 3.70
| 19.25
| 27.73
| 24.46
| 17.82
| 16.58
|
Mandate positioning
Market attention remains focused on AI infrastructure investment, which should continue supporting economic activity and corporate earnings. However, persistent inflation, higher interest rates, geopolitical uncertainty and the U.S. mid-term elections create a more complicated backdrop. We remain constructive on earnings, given resilient growth and business investment, though elevated valuations and rising unemployment warrant caution. Higher-for-longer interest rates could eventually pressure economic activity, investor sentiment and equity multiples.
Against this backdrop, we see attractive opportunities beyond AI-related areas, particularly in financials and health care, where valuations remain compelling and fundamentals solid. We are more cautious toward the consumer, as inflation, energy costs, interest rates and unemployment could pressure spending. Overall, we favour an increasingly selective, valuation-conscious approach, as market leadership broadens.
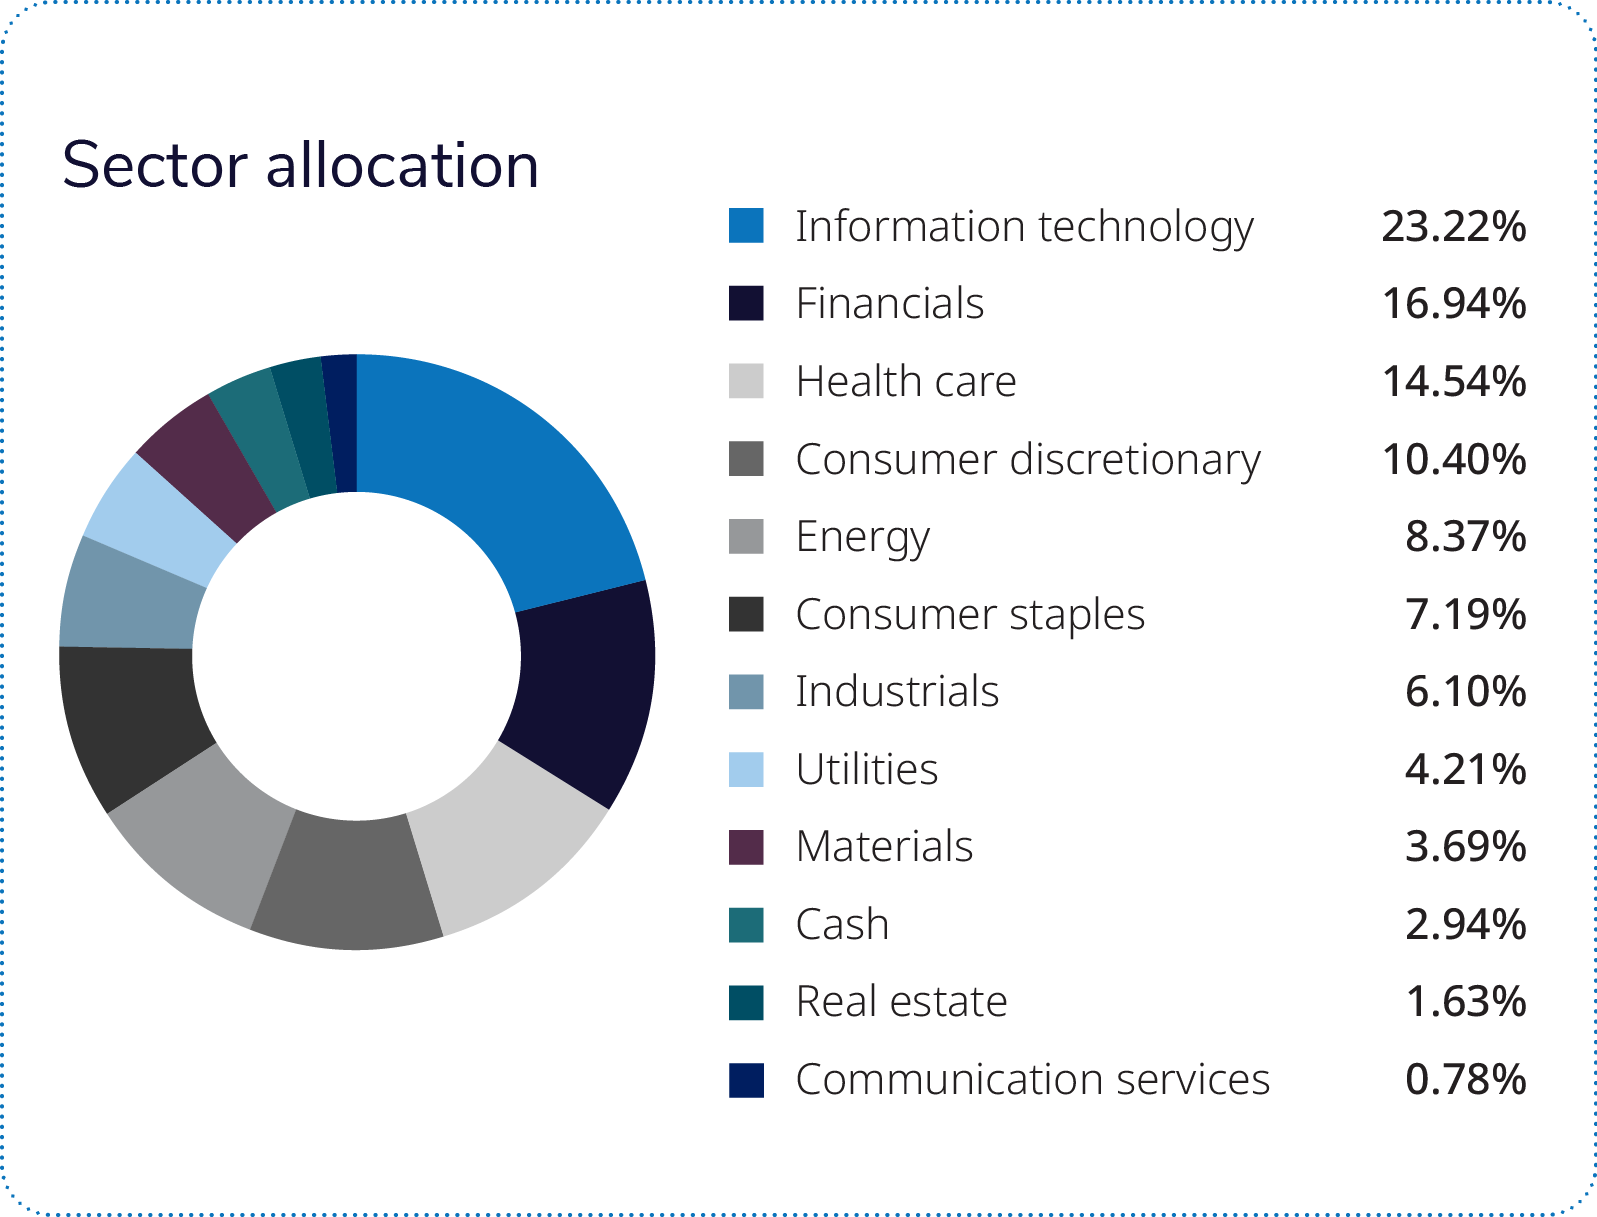
By sector, we remain within +/-5% of benchmark weight. Currently, the largest overweight sectors are information technology and health care. Industrials and communication services are the largest underweight exposures.
Market overview: earnings growth provided a powerful tailwind for equities
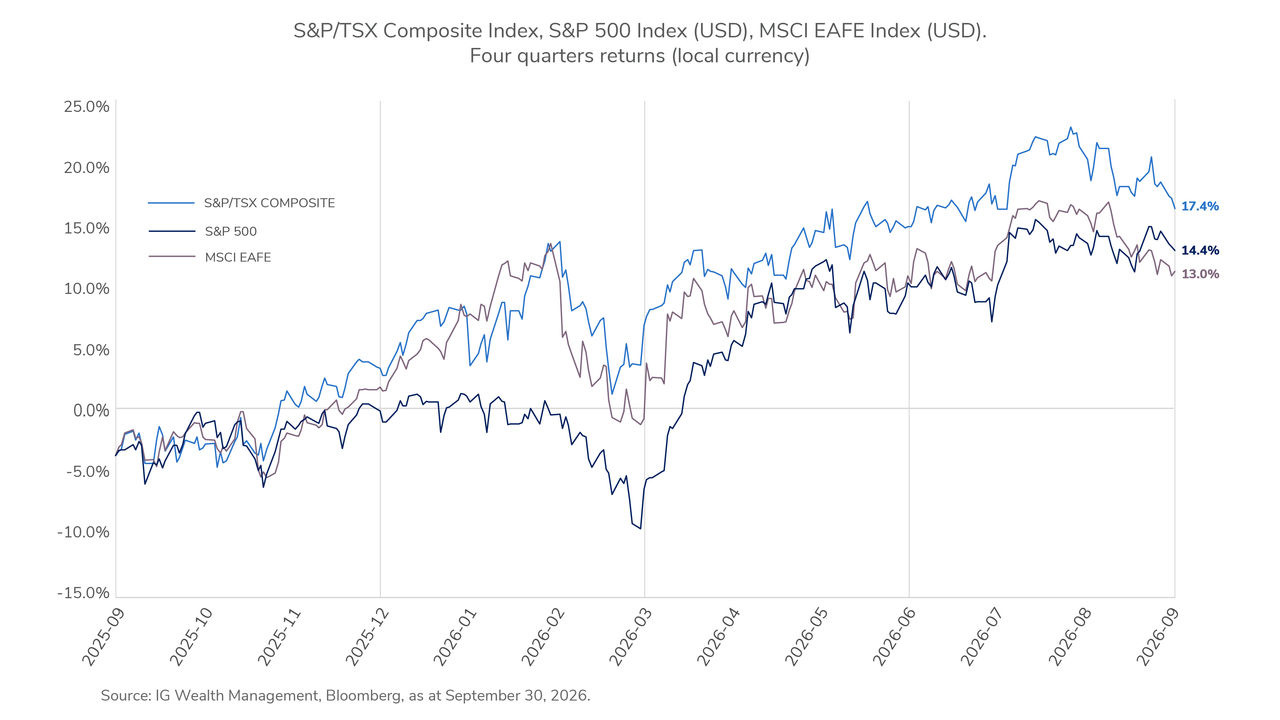
The third quarter showed that the current business cycle still has support, but risks have shifted. Growth held up, earnings improved and corporate investment remained firm, but higher oil prices, persistent inflation and rising long-term yields made the path forward less certain. Equities advanced as earnings provided fundamental support, even as higher rates raised the bar for further gains.
Canadian equities benefited from gains in resources and financials. Higher oil prices supported energy, while precious-metals companies were among the strongest performers. Bank earnings were supported by capital-markets activity, trading income and contained credit costs. U.S. equities also advanced, supported by strong earnings and continued technology investment. Higher yields weighed on more rate-sensitive areas.
International markets remained constructive overall, with parts of Asia benefiting from continued demand across the AI technology supply chain. Fixed income faced greater pressure as rising government bond yields outweighed coupon income, while credit remained comparatively resilient. Across markets, the central tension increasingly became earnings strength versus higher inflation and interest rates.
Market outlook: inflation, energy costs pushed long-term yields higher
With the recent earnings strength, the bar for market performance is higher. U.S. valuations are at the upper end of their historical range and have come under pressure from higher bond yields. Investor sentiment points to strong earnings growth going-forward, which could support equities in the near term, but the magnitude of gains may be muted.
The U.S. Federal Reserve and Bank of Canada each face two rate decisions this year, and persistent inflation has shifted central banks toward a tighter policy stance. Long-term yields remain a pressure point for equities, while also improving the income available from bonds.
The U.S. midterms may add to market volatility, but the path forward will be shaped by the economic cycle, inflation and interest rates.
To discuss your investment strategy, speak to your IG Advisor.
Azure Managed Investments™ provides discretionary investment management services distributed by IG Wealth Management Inc., Investment dealer. We will manage your Azure Managed Investments Accounts on a segregated basis in accordance with your investment policy statement and the resulting mandate selected by you. Mandates will be managed by I.G. Investment Management, Ltd. and partner organizations. You are required to make a minimum initial investment of $150,000; please read the Azure Managed Investment Account Agreement for complete details, including fees and expenses.
This commentary may contain forward-looking information, which reflects our or third-party current expectations or forecasts of future events. Forward-looking information is inherently subject to, among other things, risks, uncertainties and assumptions that could cause actual results to differ materially from those expressed herein. These risks, uncertainties and assumptions include, without limitation, general economic, political and market factors, interest and foreign exchange rates, the volatility of equity and capital markets, business competition, technological change, changes in government regulations, changes in tax laws, unexpected judicial or regulatory proceedings and catastrophic events. Please consider these and other factors carefully and do not place undue reliance on forward-looking information. The forward-looking information contained herein is current only as of September 30, 2026. There should be no expectation that such information will in all circumstances be updated, supplemented or revised, whether as a result of new information, changing circumstances, future events or otherwise.
This commentary is published by IG Wealth Management. It is provided as a general source of information. It is not intended to provide investment advice or as an endorsement of any investment. Some of the securities mentioned may be owned by IG Wealth Management or its mutual funds, or by portfolios managed by our external advisors. It may contain certain forward-looking statements regarding the market conditions which are based upon assumptions believed to be reasonable at the time of publishing. Every effort has been made to ensure that the material contained in the commentary is accurate at the time of publication, however, IG Wealth Management cannot guarantee the accuracy or the completeness of such material and accepts no responsibility for any loss arising from any use of or reliance on the information contained herein.
Past performance may not be repeated and is not indicative of future results. Actual performance may vary due to a range of factors including but not limited to current market conditions, timing of contributions and withdrawals, client-imposed restrictions, fees, expenses, tax considerations and other individual circumstances. There are no assurances that any mandate will achieve its objectives and/or avoid any losses.
Trademarks, including IG Wealth Management and IG Private Wealth Management, are owned by IGM Financial Inc. and licensed to subsidiary corporations.
©2026 IGWM Inc.