Portfolio returns: Q3 2026
| Total Return | 1M | 3M | YTD | 1YR | 3YR | 5YR | 10YR | Since Inc. (Oct 25, 2021) |
IG Climate Action Portfolio – Global Equity Balanced F | -0.09 | -2.06 | 10.15 | 11.07 | 16.26 | 7.46 | ||
Quartile rankings | 2 | 4 | 2 | 3 | 2 |
| Total Return | 1M | 3M | YTD | 1YR | 3YR | 5YR | 10YR | Since Inc. (Oct 25, 2021) |
IG Climate Action Portfolio – Global Equity Balanced F | -0.09 | -2.06 | 10.15 | 11.07 | 16.26 | 7.46 | ||
Quartile rankings | 2 | 4 | 2 | 3 | 2 |
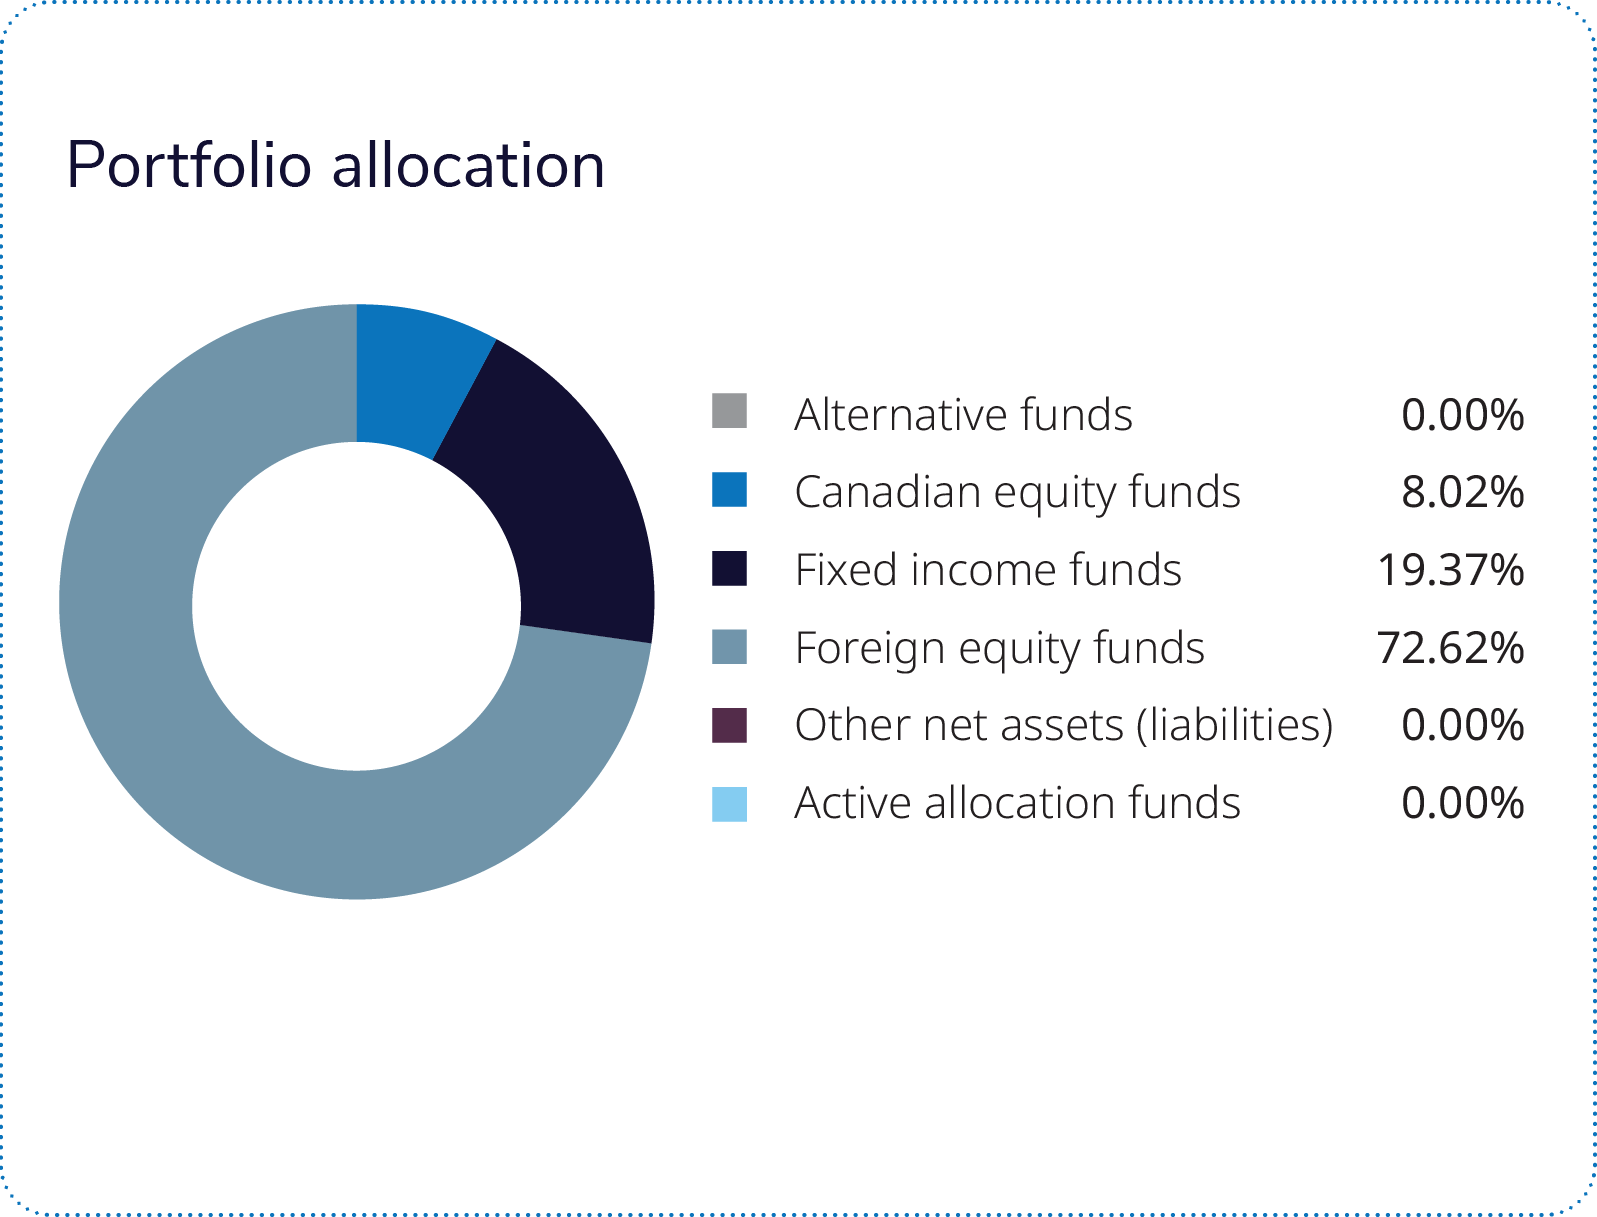 Global markets were volatile in the third quarter, as resilient economic activity and corporate earnings competed with persistent inflation, geopolitical tensions and trade uncertainty. U.S. spending and investment remained firm, while elevated inflation prompted the U.S. Federal Reserve to raise its policy rate by 25 basis points in September. In Canada, economic activity improved and the Bank of Canada held its policy rate at 2.25%.
Equities advanced despite rising bond yields. U.S. stocks reached record highs on resilient earnings, while Canadian equities also gained, supported by energy shares. Fixed income faced pressure, as persistent inflation, higher energy prices, policy tightening and heavy sovereign issuance pushed yields higher. U.S. Treasury and Government of Canada yields rose, weighing on government bonds, while credit markets were comparatively resilient.
The IG Climate Action Portfolio – Global Equity Balanced generated a negative return for the quarter.
The Mackenzie Betterworld Global Equity Fund, IG Climate Action Portfolios Betterworld Canada II and Putnam – IG Sustainable Leaders Pool were the largest contributors. The Mackenzie Betterworld Global Equity Fund generated positive returns and outperformed its benchmark, supported by stock selection and allocation effects in industrials and information technology and stock selection in energy. The IG Climate Action Portfolios Betterworld Canada II also generated positive returns and outperformed, with stock selection in industrials, materials and financials and an overweight allocation to information technology contributing positively. The Putnam – IG Sustainable Leaders Pool generated positive returns but underperformed its benchmark, with stock selection in health care and financials contributing most.
Rockefeller – IG Climate Solutions Pool, Mackenzie Greenchip Global Environmental Equity Fund and Mackenzie Canadian Sustainable Bond Fund were the largest detractors. The Rockefeller – IG Climate Solutions Pool generated negative returns and underperformed its benchmark, with stock selection and allocation effects in industrials and information technology and stock selection in financials detracting. The Mackenzie Greenchip Global Environmental Equity Fund also generated negative returns and underperformed, reflecting negative allocation effects from overweight positions in utilities and industrials and both stock selection and allocation effects in information technology. The Mackenzie Canadian Sustainable Bond Fund posted a negative return and underperformed its benchmark, as Canadian government bond yields moved higher, weighing on bond prices.
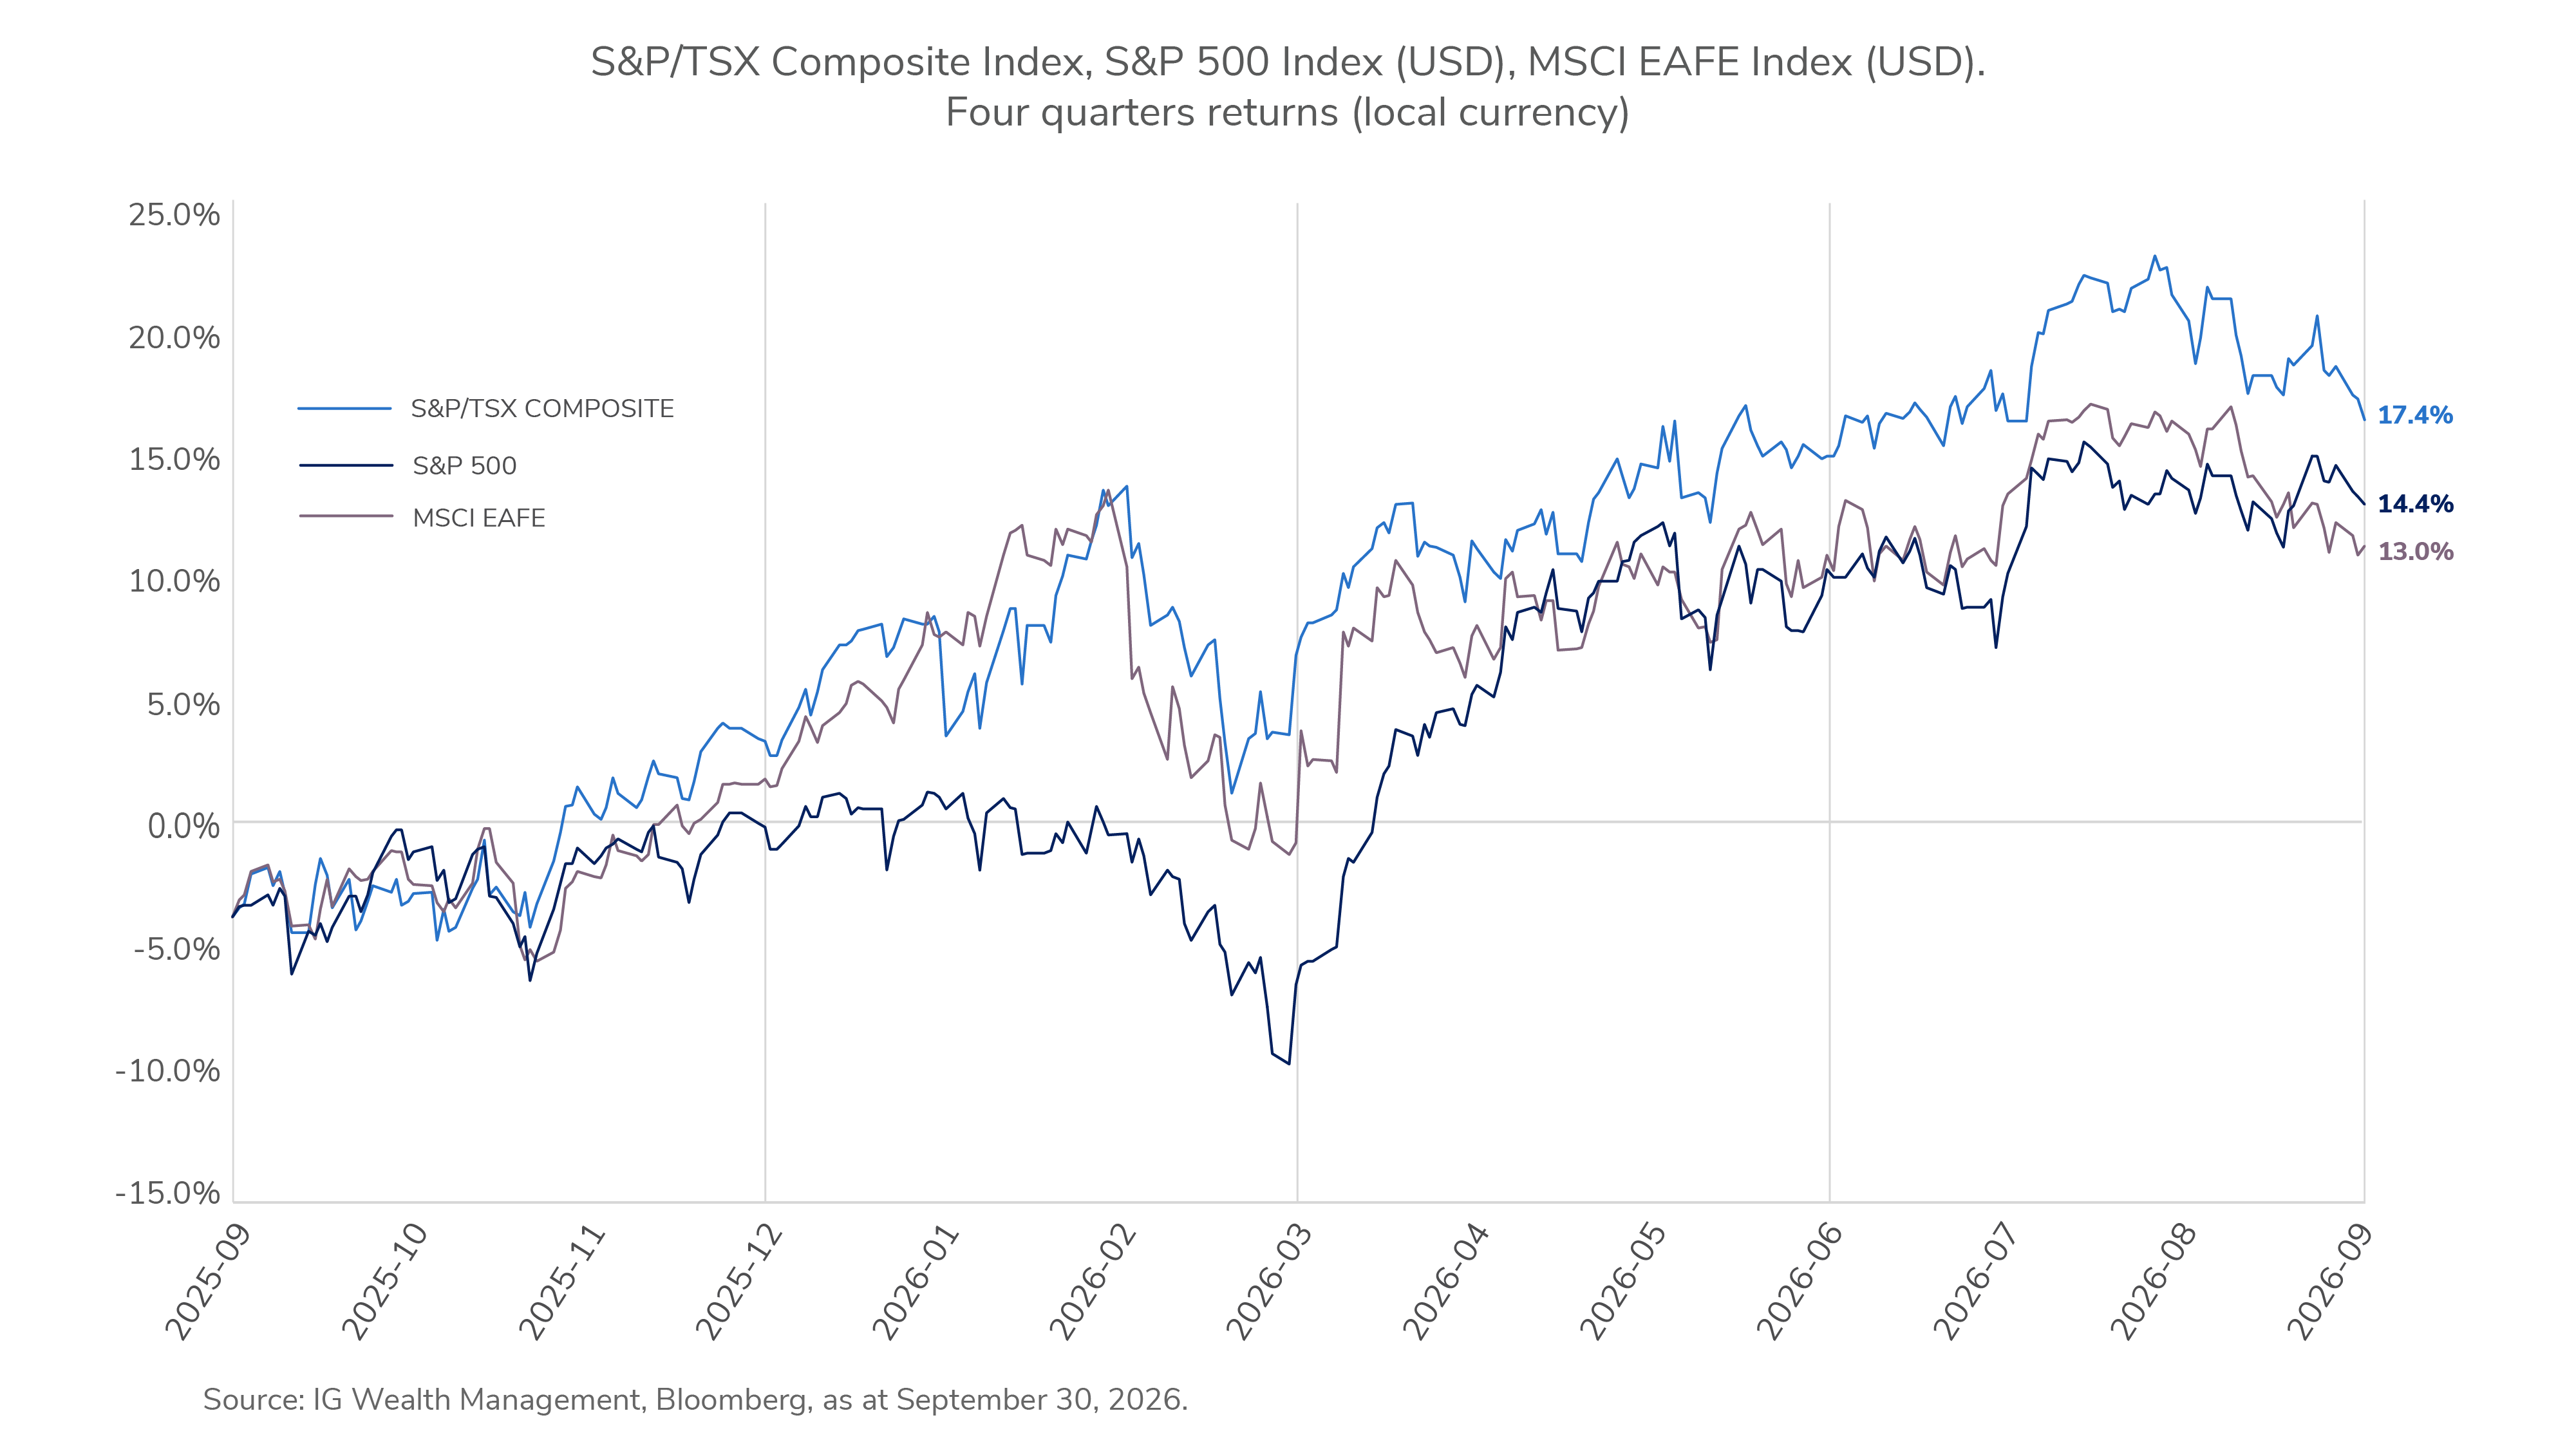
The third quarter showed that the current business cycle still has support, but risks have shifted. Growth held up, earnings improved and corporate investment remained firm, but higher oil prices, persistent inflation and rising long-term yields made the path forward less certain. Equities advanced as earnings provided fundamental support, even as higher rates raised the bar for further gains.
Canadian equities benefited from gains in resources and financials. Higher oil prices supported energy, while precious-metals companies were among the strongest performers. Bank earnings were supported by capital-markets activity, trading income and contained credit costs. U.S. equities also advanced, supported by strong earnings and continued technology investment. Higher yields weighed on more rate-sensitive areas.
International markets remained constructive overall, with parts of Asia benefiting from continued demand across the AI technology supply chain. Fixed income faced greater pressure as rising government bond yields outweighed coupon income, while credit remained comparatively resilient. Across markets, the central tension increasingly became earnings strength versus higher inflation and interest rates.
We remain overweight equities and sovereign bond duration. Equities continue to offer the most attractive opportunity among major asset classes, as elevated oil prices and yields have yet to materially weigh on earnings. At the same time, higher global yields, driven by rising real yields rather than longer-term inflation expectations, have improved the appeal of duration.
Within equities, we remain underweight Canada, where trade uncertainty with the U.S. and elevated financial-sector valuations remain headwinds. We favour developed Asia, particularly Japan, where attractive valuations and continued AI hardware spending are supportive, and maintain an overweight to U.S. small-caps, although conviction has been trimmed following strong performance. In currencies, the recent Canadian dollar sell-off has improved its valuation against the U.S. dollar, with elevated oil prices providing additional support. We also continue to favour the Japanese yen, which remains the most undervalued G7 currency.
Commissions, fees and expenses may be associated with mutual fund investments. Read the prospectus and speak to an IG Advisor before investing. The rate of return is the historical annual compounded total return as of September 30, 2026, including changes in value and reinvestment of all dividends or distributions. It does not take into account sales, redemption, distribution, optional charges or income taxes payable by any securityholder that would have reduced returns. Mutual funds are not guaranteed, values change frequently and past performance may not be repeated. Mutual funds and investment products and services are offered through the Mutual Fund Division of IG Wealth Management Inc. (in Quebec, a firm in financial planning). And additional investment products and brokerage services are offered through the Investment Dealer, IG Wealth Management Inc. (in Quebec, a firm in financial planning), a member of the Canadian Investor Protection Fund.
This commentary may contain forward-looking information which reflects our or third-party current expectations or forecasts of future events. Forward-looking information is inherently subject to, among other things, risks, uncertainties and assumptions that could cause actual results to differ materially from those expressed herein. These risks, uncertainties and assumptions include, without limitation, general economic, political and market factors, interest and foreign exchange rates, the volatility of equity and capital markets, business competition, technological change, changes in government regulations, changes in tax laws, unexpected judicial or regulatory proceedings and catastrophic events. Please consider these and other factors carefully and do not place undue reliance on forward-looking information. The forward-looking information contained herein is current only as of September 30, 2026. There should be no expectation that such information will in all circumstances be updated, supplemented or revised whether as a result of new information, changing circumstances, future events or otherwise.
This commentary is published by IG Wealth Management. It represents the views of our Portfolio Managers and is provided as a general source of information. It is not intended to provide investment advice or as an endorsement of any investment. Some of the securities mentioned may be owned by IG Wealth Management or its mutual funds, or by portfolios managed by our external advisors. Every effort has been made to ensure that the material contained in the commentary is accurate at the time of publication, however, IG Wealth Management cannot guarantee the accuracy or the completeness of such material and accepts no responsibility for any loss arising from any use of or reliance on the information contained herein.
Trademarks, including IG Wealth Management and IG Private Wealth Management, are owned by IGM Financial Inc. and licensed to subsidiary corporations.
©2026 IGWM Inc.