Portfolio returns: Q3 2026
| Total Return | 1M | 3M | YTD | 1YR | 3YR | 5YR | 10YR | Since Inc. July 12, 2013 |
IG Core Portfolio – Income F | -0.22
| -0.22
| 1.42
| 1.91
| 4.88
| 2.47
| 2.53
| 2.72
|
Quartile rankings | 2 | 2 | 2 | 2 | 2 | 2 | 1 |
| Total Return | 1M | 3M | YTD | 1YR | 3YR | 5YR | 10YR | Since Inc. July 12, 2013 |
IG Core Portfolio – Income F | -0.22
| -0.22
| 1.42
| 1.91
| 4.88
| 2.47
| 2.53
| 2.72
|
Quartile rankings | 2 | 2 | 2 | 2 | 2 | 2 | 1 |
 Fixed-income markets declined in Q3 2026 with persistent inflation, higher energy prices and shifting monetary-policy expectations pushing government bond yields higher. In the U.S., resilient economic activity and elevated inflation prompted the U.S. Federal Reserve to raise its policy rate by 25 basis points in September to 3.75%–4%. Treasury yields increased across the curve, weighing on bond prices, particularly longer-duration securities.
Canadian fixed income also faced pressure despite the Bank of Canada maintaining its policy rate at 2.25%. Concerns around inflation, trade uncertainty and rising global yields contributed to higher Government of Canada bond yields. Longer-duration bonds experienced greater losses, while shorter-maturity securities demonstrated relatively greater resilience. Canadian investment-grade bonds declined, with government securities particularly sensitive to the rise in yields.
Credit markets generally held up better than government bonds, although performance varied across quality segments. Investment-grade corporate credit benefited from comparatively stable spreads and continued investor demand, while lower-rated credit faced greater pressure with financing costs increasing. High-yield bonds proved more resilient than longer-duration government debt over the quarter, supported by higher coupon income and lower interest-rate sensitivity. Overall, duration was a key driver of fixed-income performance, with rising yields outweighing income for many government-bond exposures.
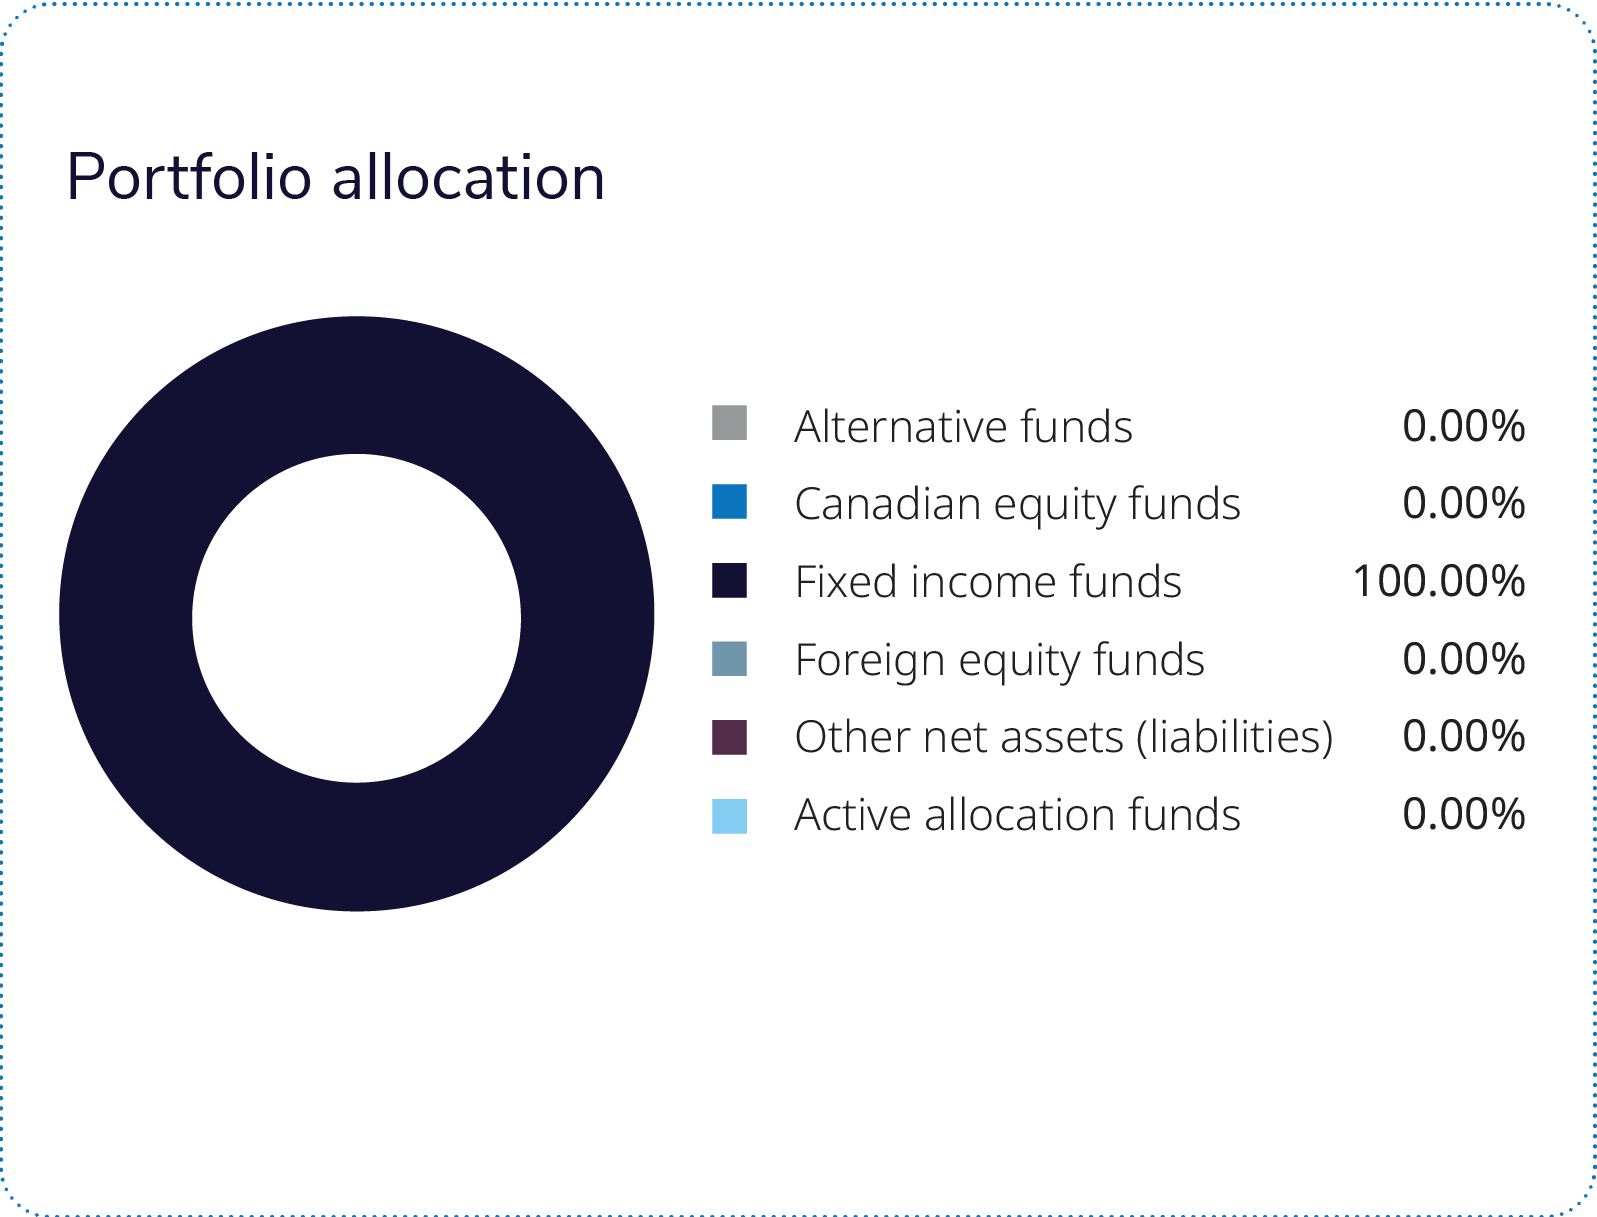
During the quarter, the portfolio generated a negative return with fixed income being a major detractor. The portfolio's performance was heavily driven by its core fixed-income sleeve especially the Mackenzie – IG Canadian Corporate Bond Pool which detracted from portfolio performance but outperformed its benchmark. Energy, financials and infrastructure bonds weighed on absolute returns, while favourable corporate security selection boosted relative performance. Government-related bond exposure also faced pressure from rising yields during the quarter. The IG Mackenzie Mortgage and Short-Term Income Fund declined modestly during the quarter but outperformed its benchmark. Government bonds were the largest detractors, particularly provincial and federal securities, followed by corporate bonds, primarily financials. Positive contributions from mortgage investments and cash partially offset these losses.
Exposure to the IG Mackenzie Canadian Money Market Fund, specifically the defensive and liquid sleeves of the portfolio, supported positively during the quarter. Outside of core fixed income, the IG Mackenzie Real Property Fund also added positively to the return.
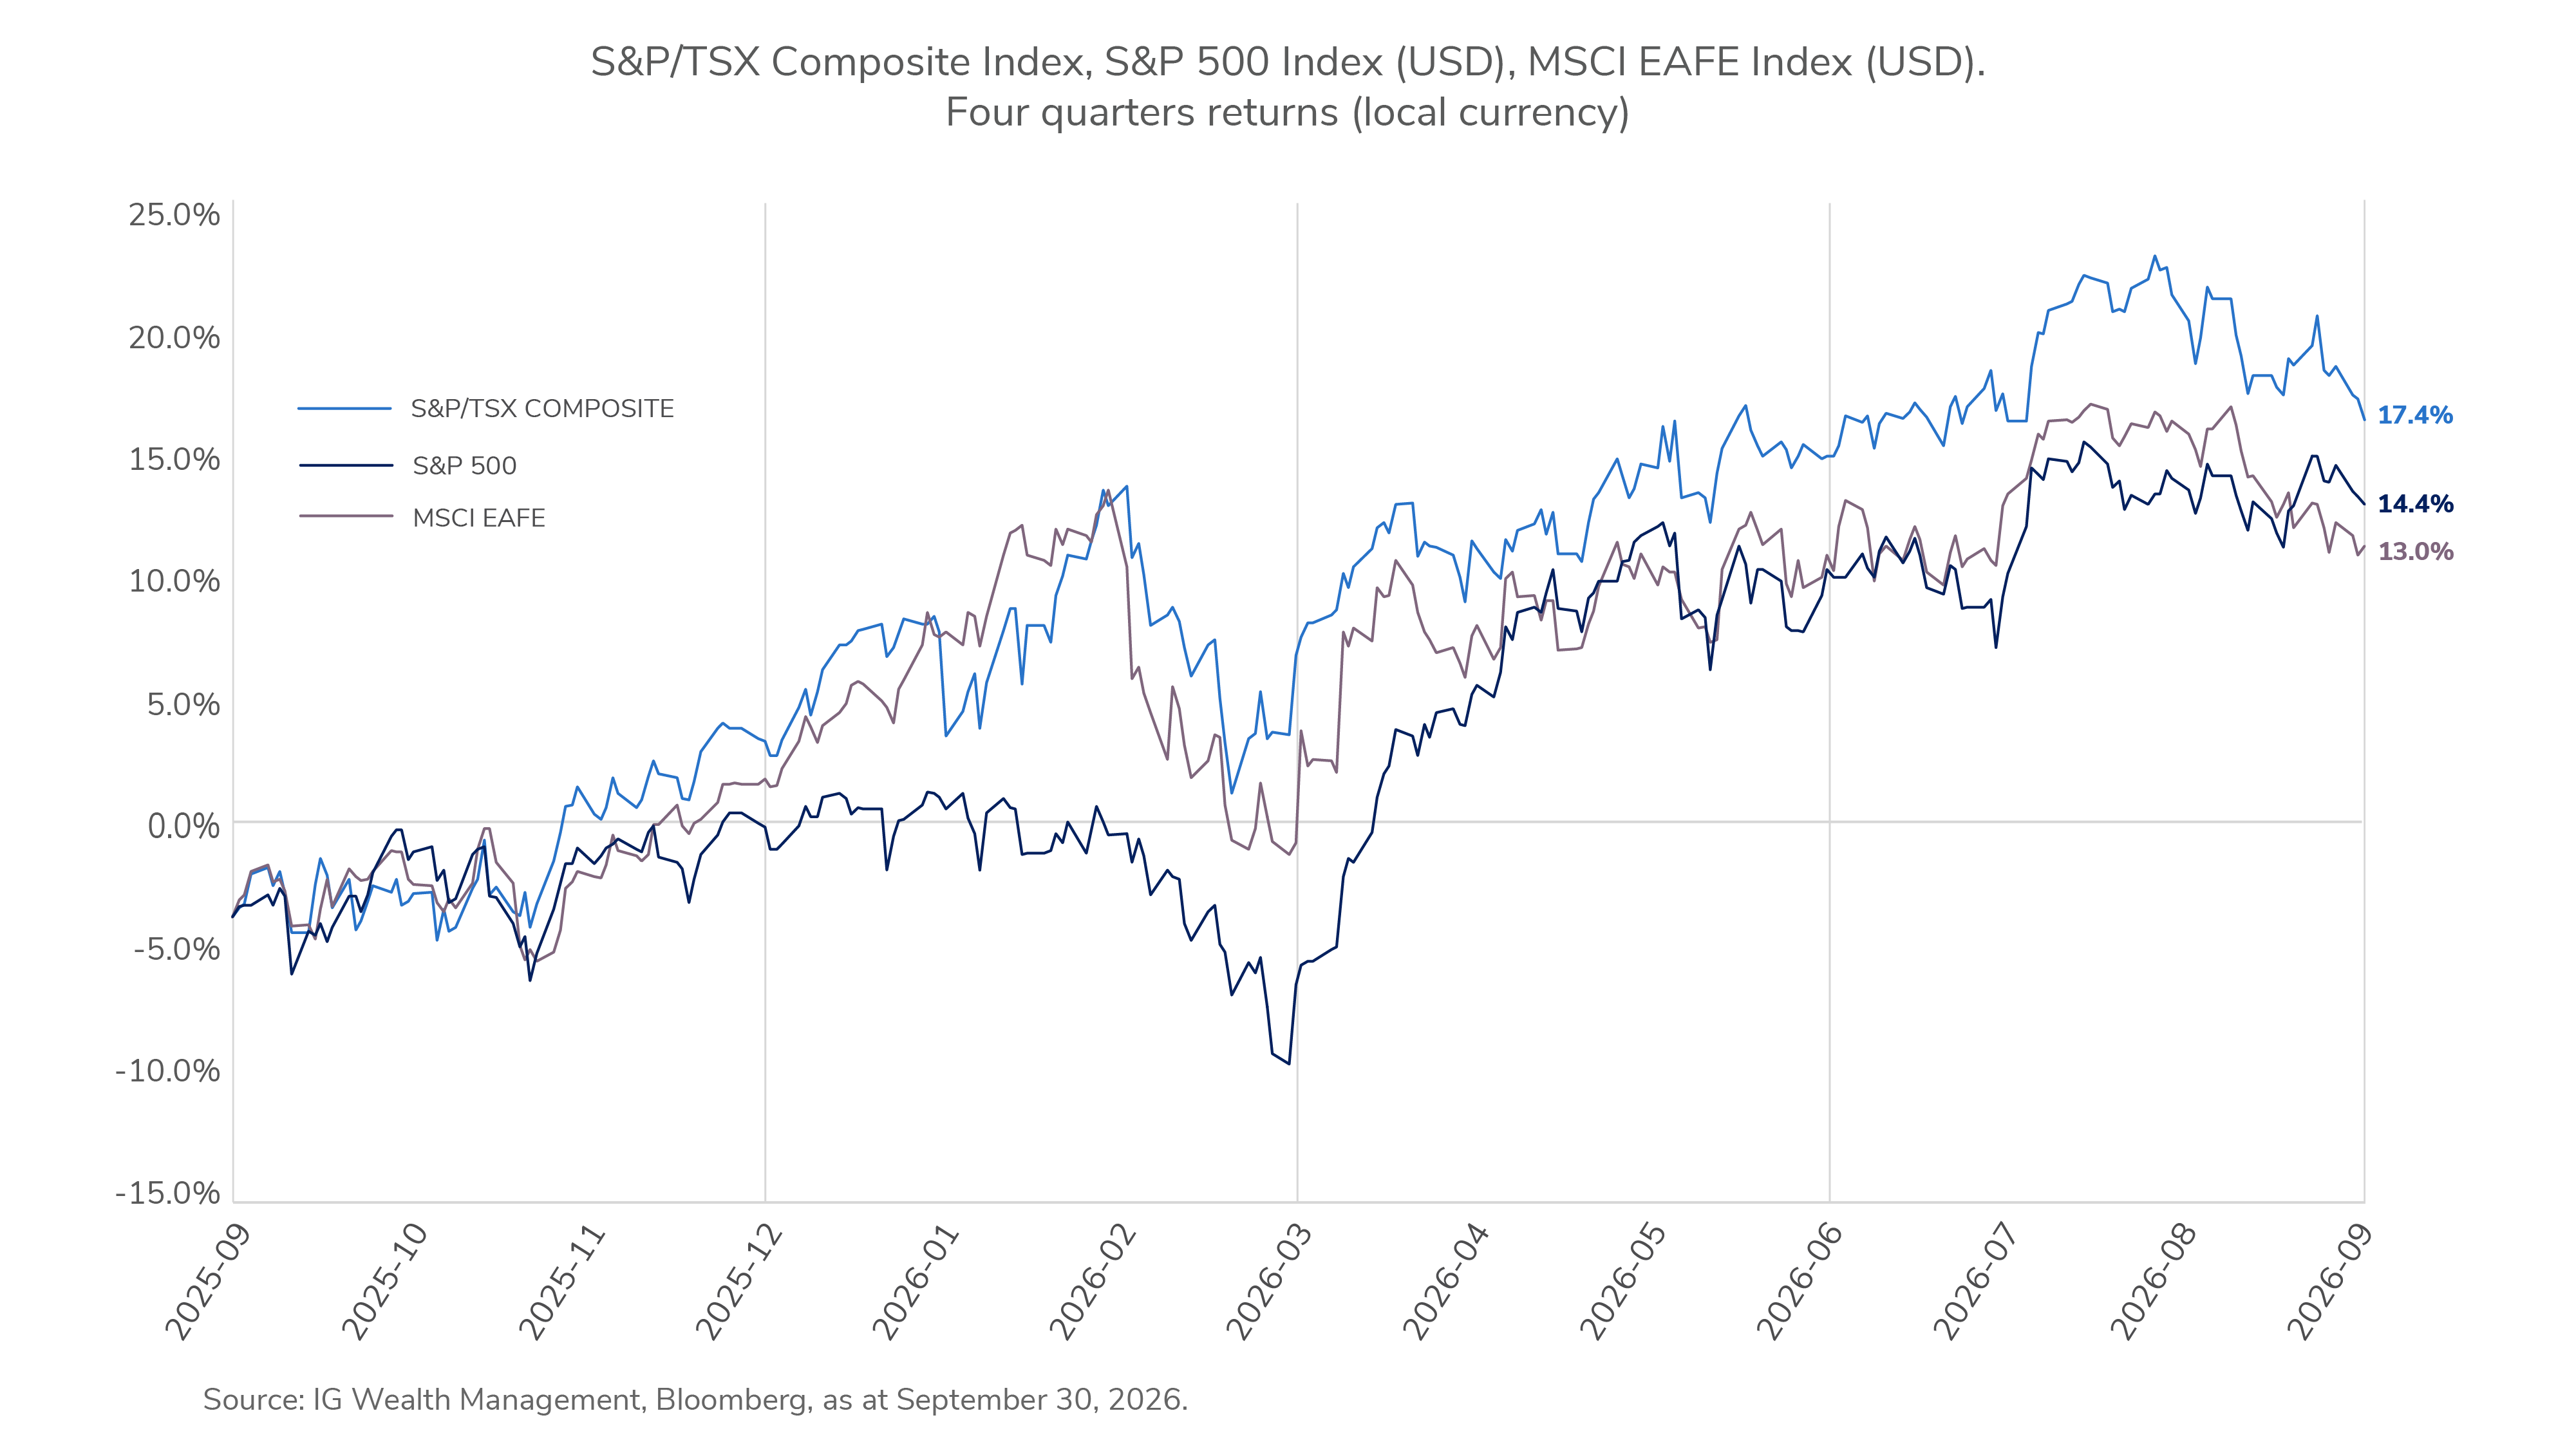
The third quarter showed that the current business cycle still has support, but risks have shifted. Growth held up, earnings improved and corporate investment remained firm, but higher oil prices, persistent inflation and rising long-term yields made the path forward less certain. Equities advanced as earnings provided fundamental support, even as higher rates raised the bar for further gains.
Canadian equities benefited from gains in resources and financials. Higher oil prices supported energy, while precious-metals companies were among the strongest performers. Bank earnings were supported by capital-markets activity, trading income and contained credit costs. U.S. equities also advanced, supported by strong earnings and continued technology investment. Higher yields weighed on more rate-sensitive areas.
International markets remained constructive overall, with parts of Asia benefiting from continued demand across the AI technology supply chain. Fixed income faced greater pressure as rising government bond yields outweighed coupon income, while credit remained comparatively resilient. Across markets, the central tension increasingly became earnings strength versus higher inflation and interest rates.
So far, 2026 has been defined by the drastic rise in yields across developed markets, led by the U.S. The outlook for Q4 depends on whether the drivers of this increase remain, are tempered or reverse. We see three primary drivers: stubbornly high inflation supported by elevated energy costs, debt and deficit concerns, and continued outsized corporate issuance led by hyperscalers and the AI buildout.
Of these, only a reversal in energy prices seems realistically possible. The AI buildout is a game of survival for hyperscalers, and higher yields are unlikely to be a deterrent. As such, adding duration, even at relatively elevated yield levels, remains unattractive.
Higher yields have made corporate debt attractive from an all-in yield perspective, keeping credit spreads tight despite a more fragile market. We therefore favour alternative opportunities to add carry, such as emerging-market debt, and relative-value opportunities rather than outright duration. One area we are monitoring for Q4 is the rapidly widening spread between U.S. and Canadian government bonds, which increased by 30–35 basis points across the 10-year and 30-year maturities during Q3.
Commissions, fees and expenses may be associated with mutual fund investments. Read the prospectus and speak to an IG Advisor before investing. The rate of return is the historical annual compounded total return as of September 30, 2026, including changes in value and reinvestment of all dividends or distributions. It does not take into account sales, redemption, distribution, optional charges or income taxes payable by any securityholder that would have reduced returns. Mutual funds are not guaranteed, values change frequently and past performance may not be repeated. Mutual funds and investment products and services are offered through the Mutual Fund Division of IG Wealth Management Inc. (in Quebec, a firm in financial planning). And additional investment products and brokerage services are offered through the Investment Dealer, IG Wealth Management Inc. (in Quebec, a firm in financial planning), a member of the Canadian Investor Protection Fund.
This commentary may contain forward-looking information which reflects our or third-party current expectations or forecasts of future events. Forward-looking information is inherently subject to, among other things, risks, uncertainties and assumptions that could cause actual results to differ materially from those expressed herein. These risks, uncertainties and assumptions include, without limitation, general economic, political and market factors, interest and foreign exchange rates, the volatility of equity and capital markets, business competition, technological change, changes in government regulations, changes in tax laws, unexpected judicial or regulatory proceedings and catastrophic events. Please consider these and other factors carefully and do not place undue reliance on forward-looking information. The forward-looking information contained herein is current only as of September 30, 2026. There should be no expectation that such information will in all circumstances be updated, supplemented or revised whether as a result of new information, changing circumstances, future events or otherwise.
This commentary is published by IG Wealth Management. It represents the views of our Portfolio Managers and is provided as a general source of information. It is not intended to provide investment advice or as an endorsement of any investment. Some of the securities mentioned may be owned by IG Wealth Management or its mutual funds, or by portfolios managed by our external advisors. Every effort has been made to ensure that the material contained in the commentary is accurate at the time of publication, however, IG Wealth Management cannot guarantee the accuracy or the completeness of such material and accepts no responsibility for any loss arising from any use of or reliance on the information contained herein.
Trademarks, including IG Wealth Management and IG Private Wealth Management, are owned by IGM Financial Inc. and licensed to subsidiary corporations.
©2026 IGWM Inc.