Portfolio returns: Q3 2026
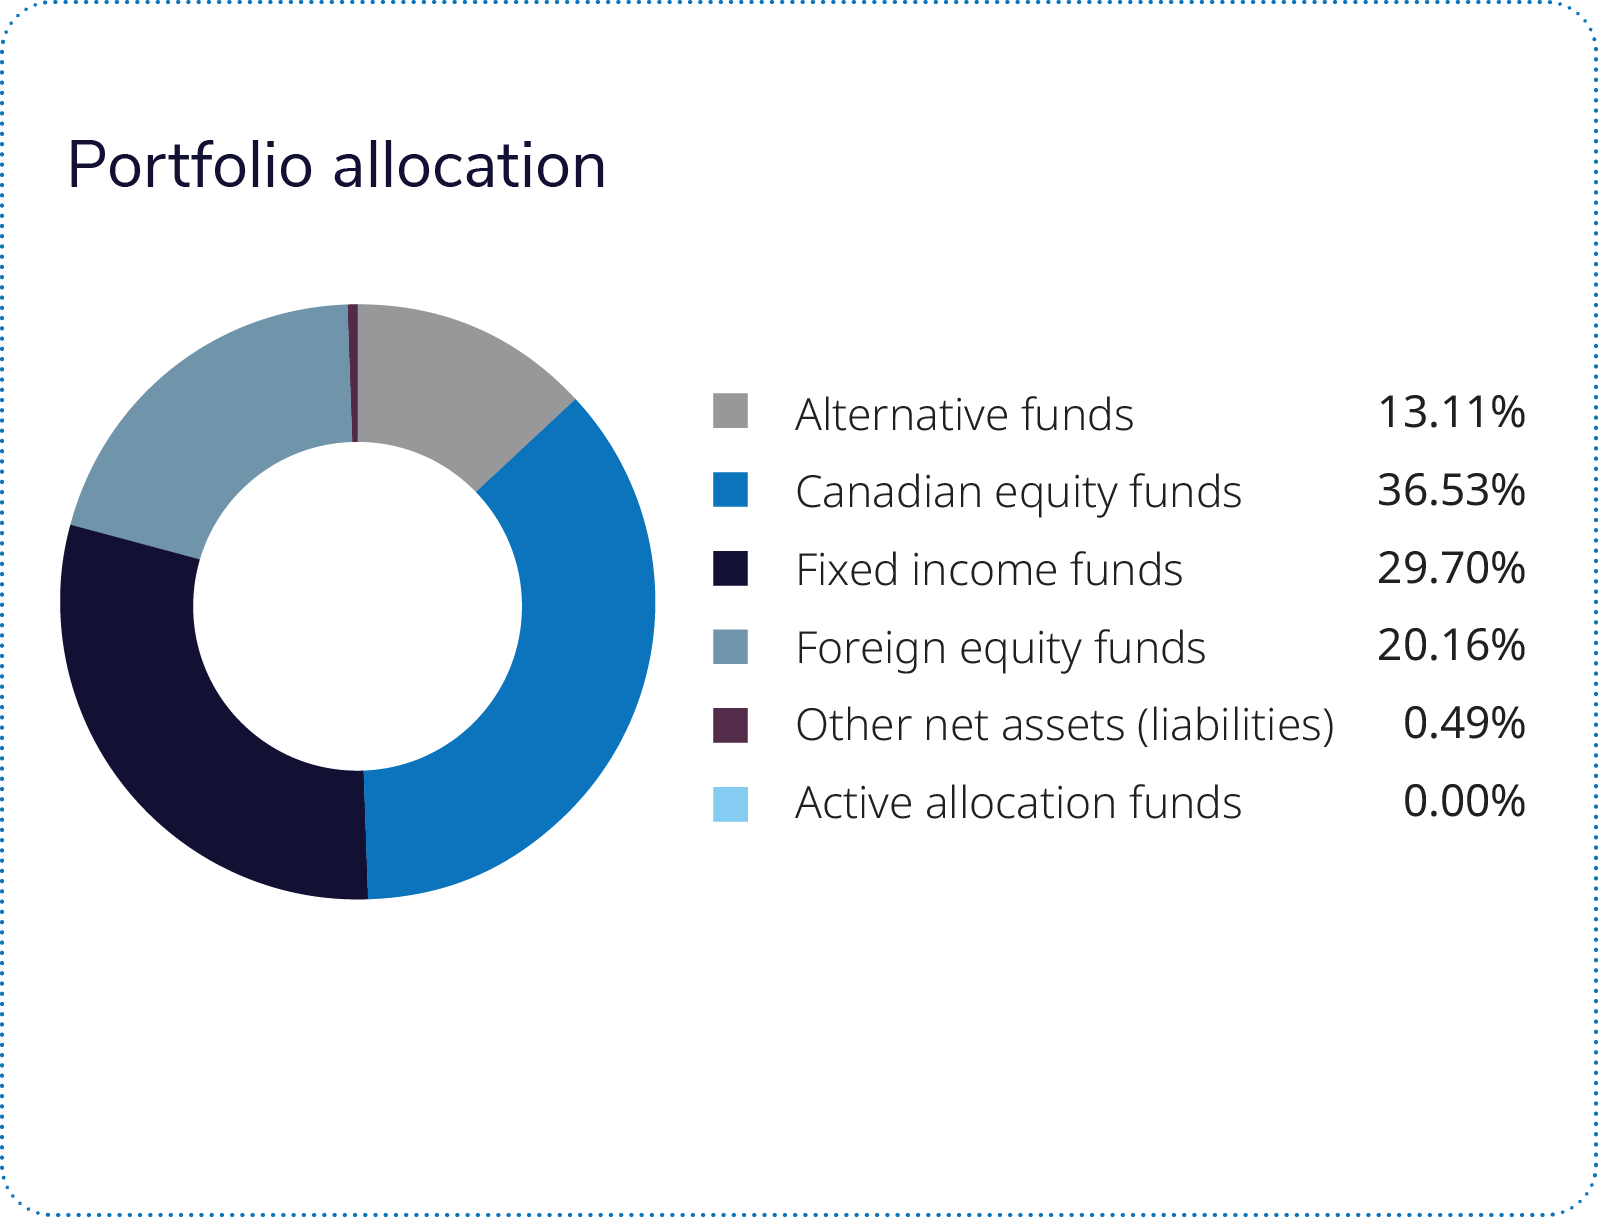
| Total Return | 1M | 3M | YTD | 1YR | 3YR | 5YR | 10YR | Since Inc. (Jul 12, 2013) |
IG Growth Portfolio – Canadian Balanced F | -1.29
| 0.06
| 8.21
| 11.11
| 15.64
| 7.99
| 6.72
| 6.78
|
Quartile rankings | 2 | 1 | 1 | 1 | 1 | 1 | 2 |
| Total Return | 1M | 3M | YTD | 1YR | 3YR | 5YR | 10YR | Since Inc. (Jul 12, 2013) |
IG Growth Portfolio – Canadian Balanced F | -1.29
| 0.06
| 8.21
| 11.11
| 15.64
| 7.99
| 6.72
| 6.78
|
Quartile rankings | 2 | 1 | 1 | 1 | 1 | 1 | 2 |
 Global markets navigated a volatile third quarter, as resilient economic activity and corporate earnings competed with persistent inflation, geopolitical tensions and trade uncertainty. U.S. spending and investment remained firm, while elevated inflation prompted the U.S. Federal Reserve to raise its policy rate by 25 basis points (a quarter of a percentage point) in September. In Canada, economic activity improved following earlier weakness, while the Bank of Canada held its policy rate at 2.25%.
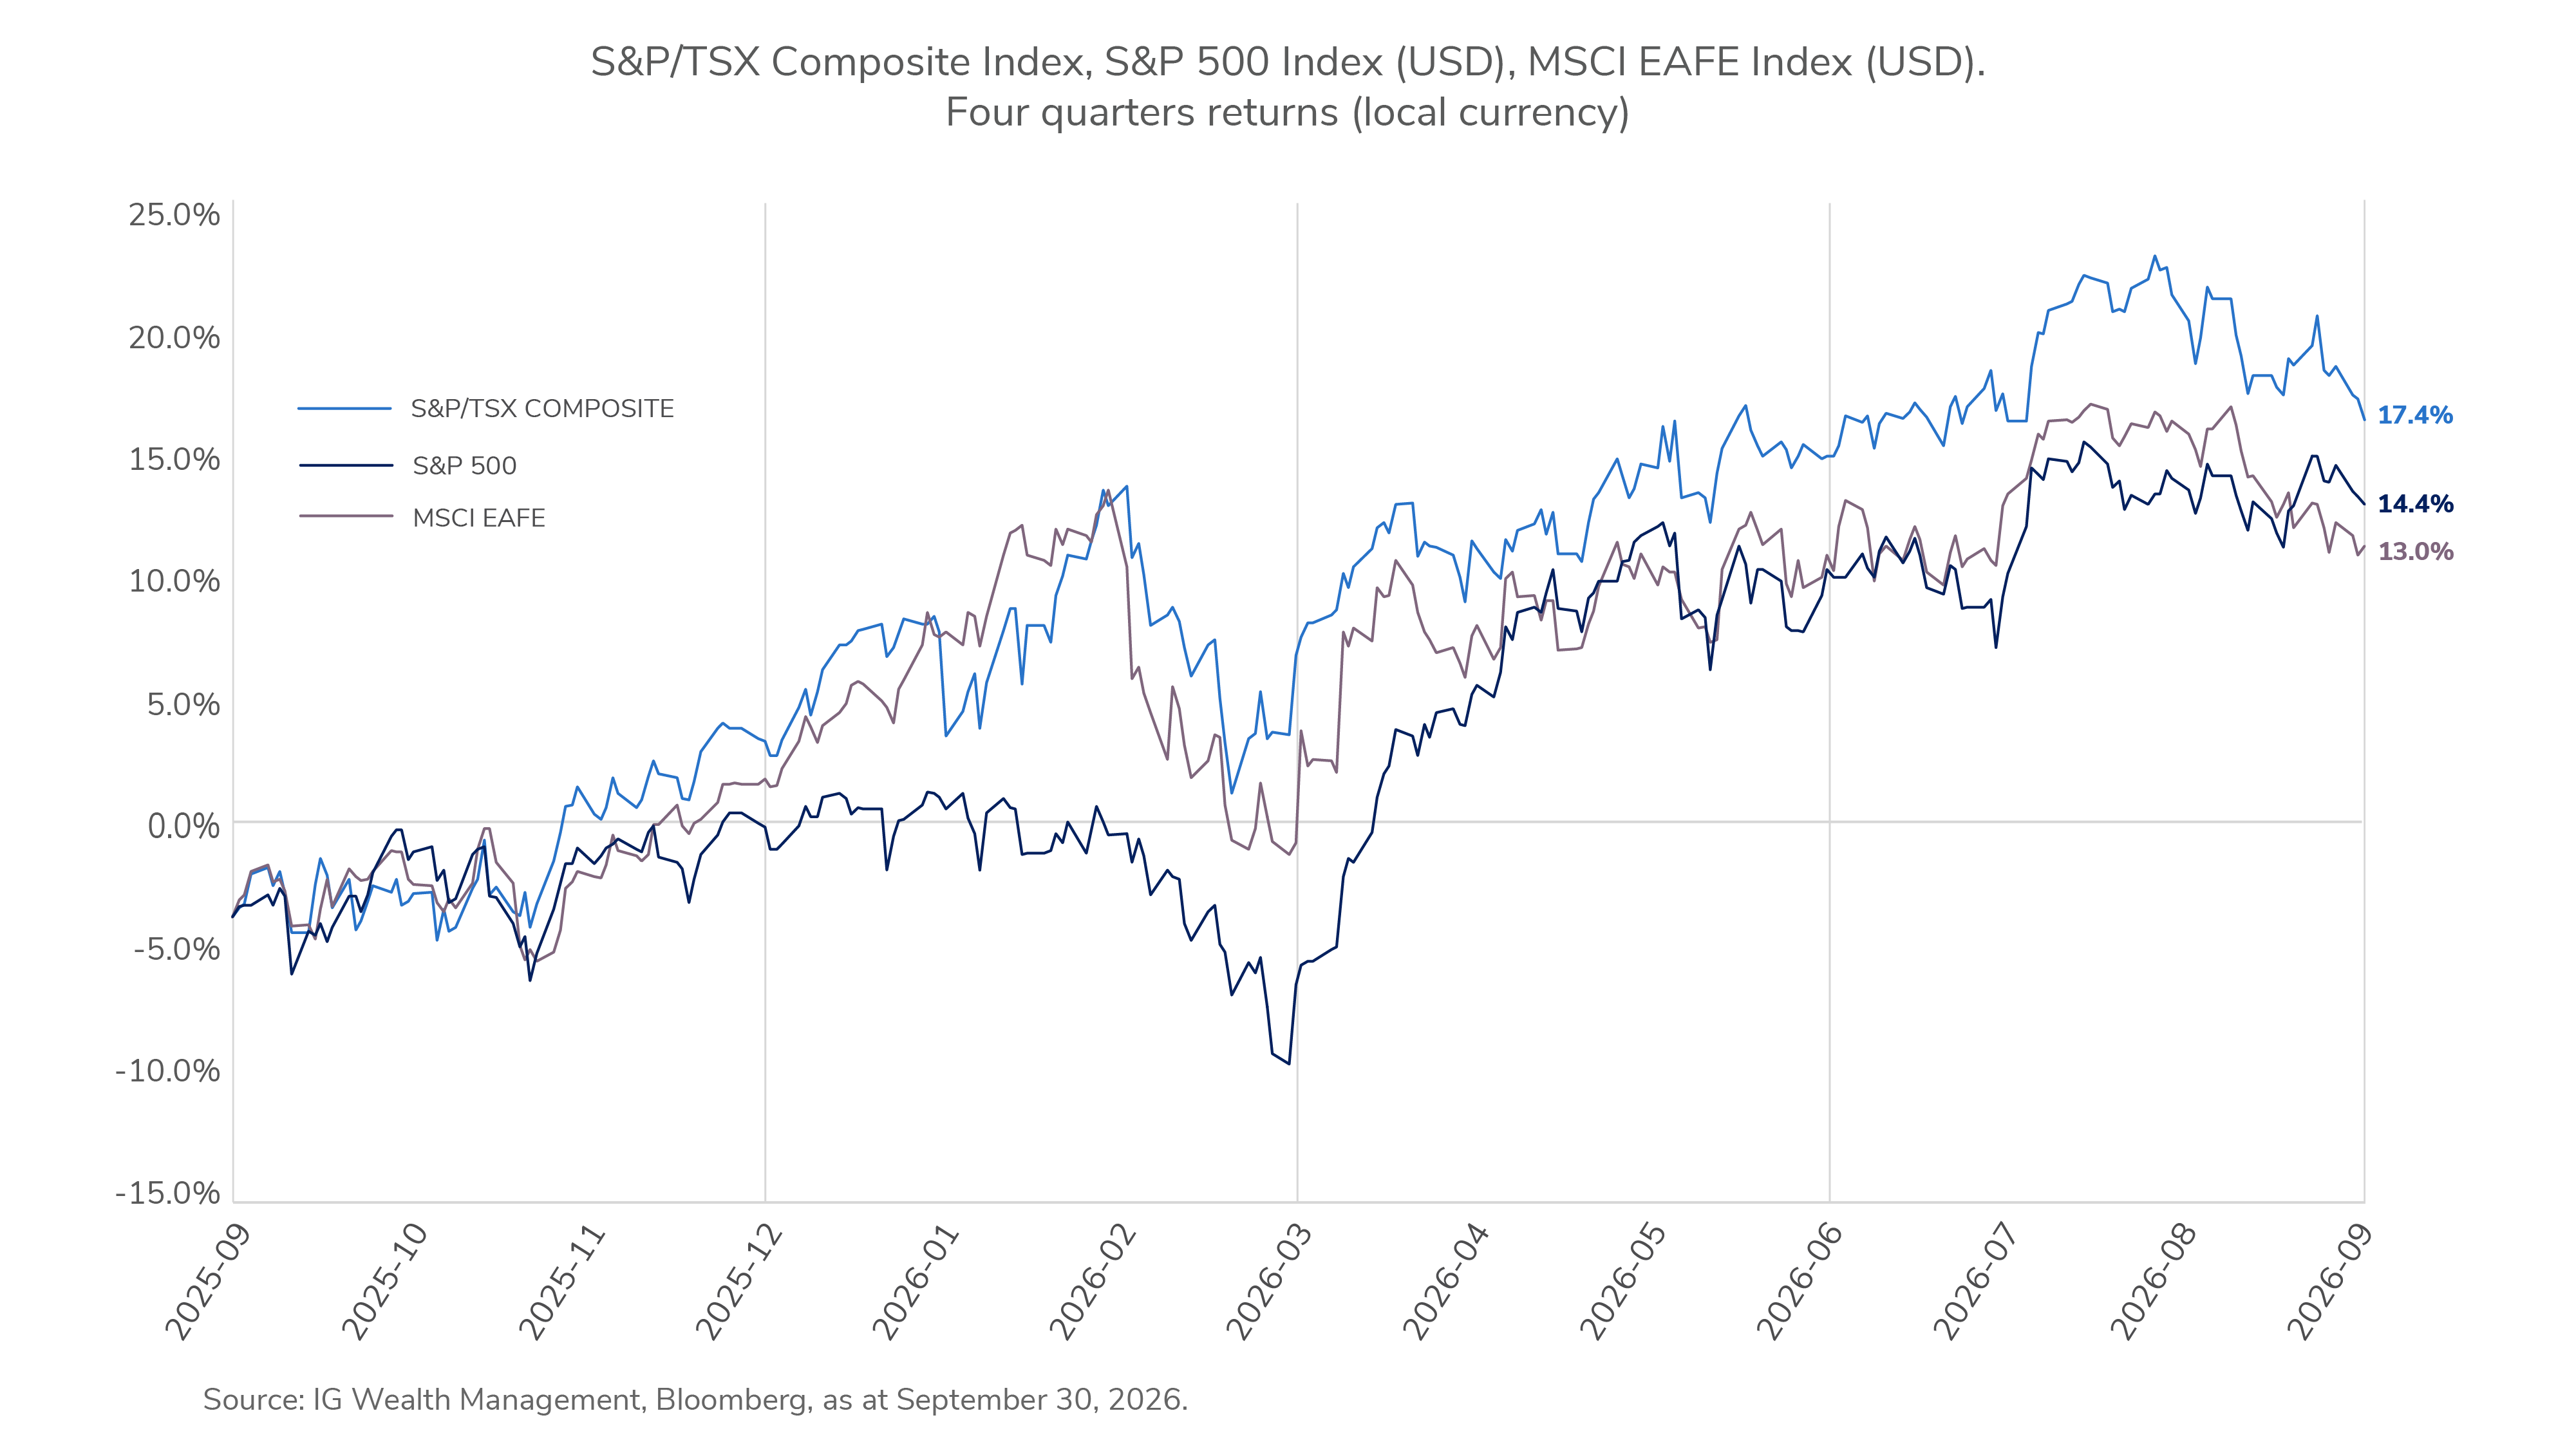
Equities advanced despite rising bond yields. U.S. stocks reached record highs, supported by resilient earnings, although market leadership remained concentrated. Canadian equities also gained, helped by strength in energy shares, as oil prices rose, while performance across international markets was mixed.
Fixed income faced pressure, as persistent inflation, higher energy prices, policy tightening and heavy sovereign issuance pushed yields higher. U.S. Treasury yields rose significantly, weighing on government bonds. Canadian bonds also declined, as Government of Canada yields increased materially across the curve despite an unchanged policy rate, while credit markets proved comparatively resilient.
The IG Growth Portfolio – Canadian Balanced generated a modest positive return over the quarter.
The largest contributors were the Mackenzie Canadian Equity Pool, Mackenzie Broad Risk Premia Collection Fund and Mackenzie IG U.S. Equity Pool. The Mackenzie Canadian Equity Pool outperformed its benchmark, supported by strong security selection in energy and industrials, alongside underweight allocations to industrials and communication services. Security selection in materials and an overweight in financials detracted. The Mackenzie Broad Risk Premia Collection Fund (which combines equity exposure with alternative strategies in a capital-efficient manner) contributed positively, led by FX timing and cross-sectional equity strategies. The Mackenzie IG U.S. Equity Pool modestly underperformed its benchmark, primarily due to an underweight allocation and weaker security selection in information technology, alongside weak selection in health care and financials. Allocation effects in industrials and utilities contributed modestly.
The largest detractors were the Mackenzie IG Canadian Bond Pool, Mackenzie Enhanced Fixed Income Risk Premia Fund and Mackenzie US Quantitative Small Cap Fund. The Mackenzie IG Canadian Bond Pool performed broadly in line with its benchmark, as benefits from an underweight in government bonds and favourable yield-curve movements were offset by adverse yield-shift effects from its corporate bond overweight. The Mackenzie Enhanced Fixed Income Risk Premia Fund (a levered alternative fixed income strategy used to efficiently manage portfolio exposure) detracted, as rising yields pressured bond prices. The Mackenzie US Quantitative Small Cap Fund underperformed its benchmark, primarily due to weak security selection in health care, information technology, industrials, financials and materials. An overweight in energy and strong security selection within the sector contributed positively.
The third quarter showed that the current business cycle still has support, but risks have shifted. Growth held up, earnings improved and corporate investment remained firm, but higher oil prices, persistent inflation and rising long-term yields made the path forward less certain. Equities advanced as earnings provided fundamental support, even as higher rates raised the bar for further gains.
Canadian equities benefited from gains in resources and financials. Higher oil prices supported energy, while precious-metals companies were among the strongest performers. Bank earnings were supported by capital-markets activity, trading income and contained credit costs. U.S. equities also advanced, supported by strong earnings and continued technology investment. Higher yields weighed on more rate-sensitive areas.
International markets remained constructive overall, with parts of Asia benefiting from continued demand across the AI technology supply chain. Fixed income faced greater pressure as rising government bond yields outweighed coupon income, while credit remained comparatively resilient. Across markets, the central tension increasingly became earnings strength versus higher inflation and interest rates.
We remain overweight equities and sovereign bond duration. Equities continue to offer the most attractive opportunity among major asset classes, as elevated oil prices and yields have yet to materially weigh on earnings. At the same time, higher global yields, driven by rising real yields rather than longer-term inflation expectations, have improved the appeal of duration.
Within equities, we remain underweight Canada, where trade uncertainty with the U.S. and elevated financial-sector valuations remain headwinds. We favour developed Asia, particularly Japan, where attractive valuations and continued AI hardware spending are supportive, and maintain an overweight position to U.S. small-caps, although conviction has been trimmed following strong performance. In currencies, the recent Canadian dollar sell-off has improved its valuation against the U.S. dollar, with elevated oil prices providing additional support. We also continue to favour the Japanese yen, which remains the most undervalued G7 currency.
Commissions, fees and expenses may be associated with mutual fund investments. Read the prospectus and speak to an IG Advisor before investing. The rate of return is the historical annual compounded total return as of September 30, 2026, including changes in value and reinvestment of all dividends or distributions. It does not take into account sales, redemption, distribution, optional charges or income taxes payable by any securityholder that would have reduced returns. Mutual funds are not guaranteed, values change frequently and past performance may not be repeated. Mutual funds and investment products and services are offered through the Mutual Fund Division of IG Wealth Management Inc. (in Quebec, a firm in financial planning). And additional investment products and brokerage services are offered through the Investment Dealer, IG Wealth Management Inc. (in Quebec, a firm in financial planning), a member of the Canadian Investor Protection Fund.
This commentary may contain forward-looking information which reflects our or third-party current expectations or forecasts of future events. Forward-looking information is inherently subject to, among other things, risks, uncertainties and assumptions that could cause actual results to differ materially from those expressed herein. These risks, uncertainties and assumptions include, without limitation, general economic, political and market factors, interest and foreign exchange rates, the volatility of equity and capital markets, business competition, technological change, changes in government regulations, changes in tax laws, unexpected judicial or regulatory proceedings and catastrophic events. Please consider these and other factors carefully and do not place undue reliance on forward-looking information. The forward-looking information contained herein is current only as of September 30, 2026. There should be no expectation that such information will in all circumstances be updated, supplemented or revised whether as a result of new information, changing circumstances, future events or otherwise.
This commentary is published by IG Wealth Management. It represents the views of our Portfolio Managers and is provided as a general source of information. It is not intended to provide investment advice or as an endorsement of any investment. Some of the securities mentioned may be owned by IG Wealth Management or its mutual funds, or by portfolios managed by our external advisors. Every effort has been made to ensure that the material contained in the commentary is accurate at the time of publication, however, IG Wealth Management cannot guarantee the accuracy or the completeness of such material and accepts no responsibility for any loss arising from any use of or reliance on the information contained herein.
Trademarks, including IG Wealth Management and IG Private Wealth Management, are owned by IGM Financial Inc. and licensed to subsidiary corporations.
©2026 IGWM Inc.