Portfolio returns: Q3 2026
| Total Return | 1M | 3M | YTD | 1YR | 3YR | 5YR | 10YR | Since Inc. (Jan 30, 2023) |
IG Graduation Portfolio F | -0.55
| -0.79
| 0.77
| 1.16
| 5.29
| 4.17
| ||
Quartile rankings | 2 | 3 | 2 | 2 | 1 |
| Total Return | 1M | 3M | YTD | 1YR | 3YR | 5YR | 10YR | Since Inc. (Jan 30, 2023) |
IG Graduation Portfolio F | -0.55
| -0.79
| 0.77
| 1.16
| 5.29
| 4.17
| ||
Quartile rankings | 2 | 3 | 2 | 2 | 1 |
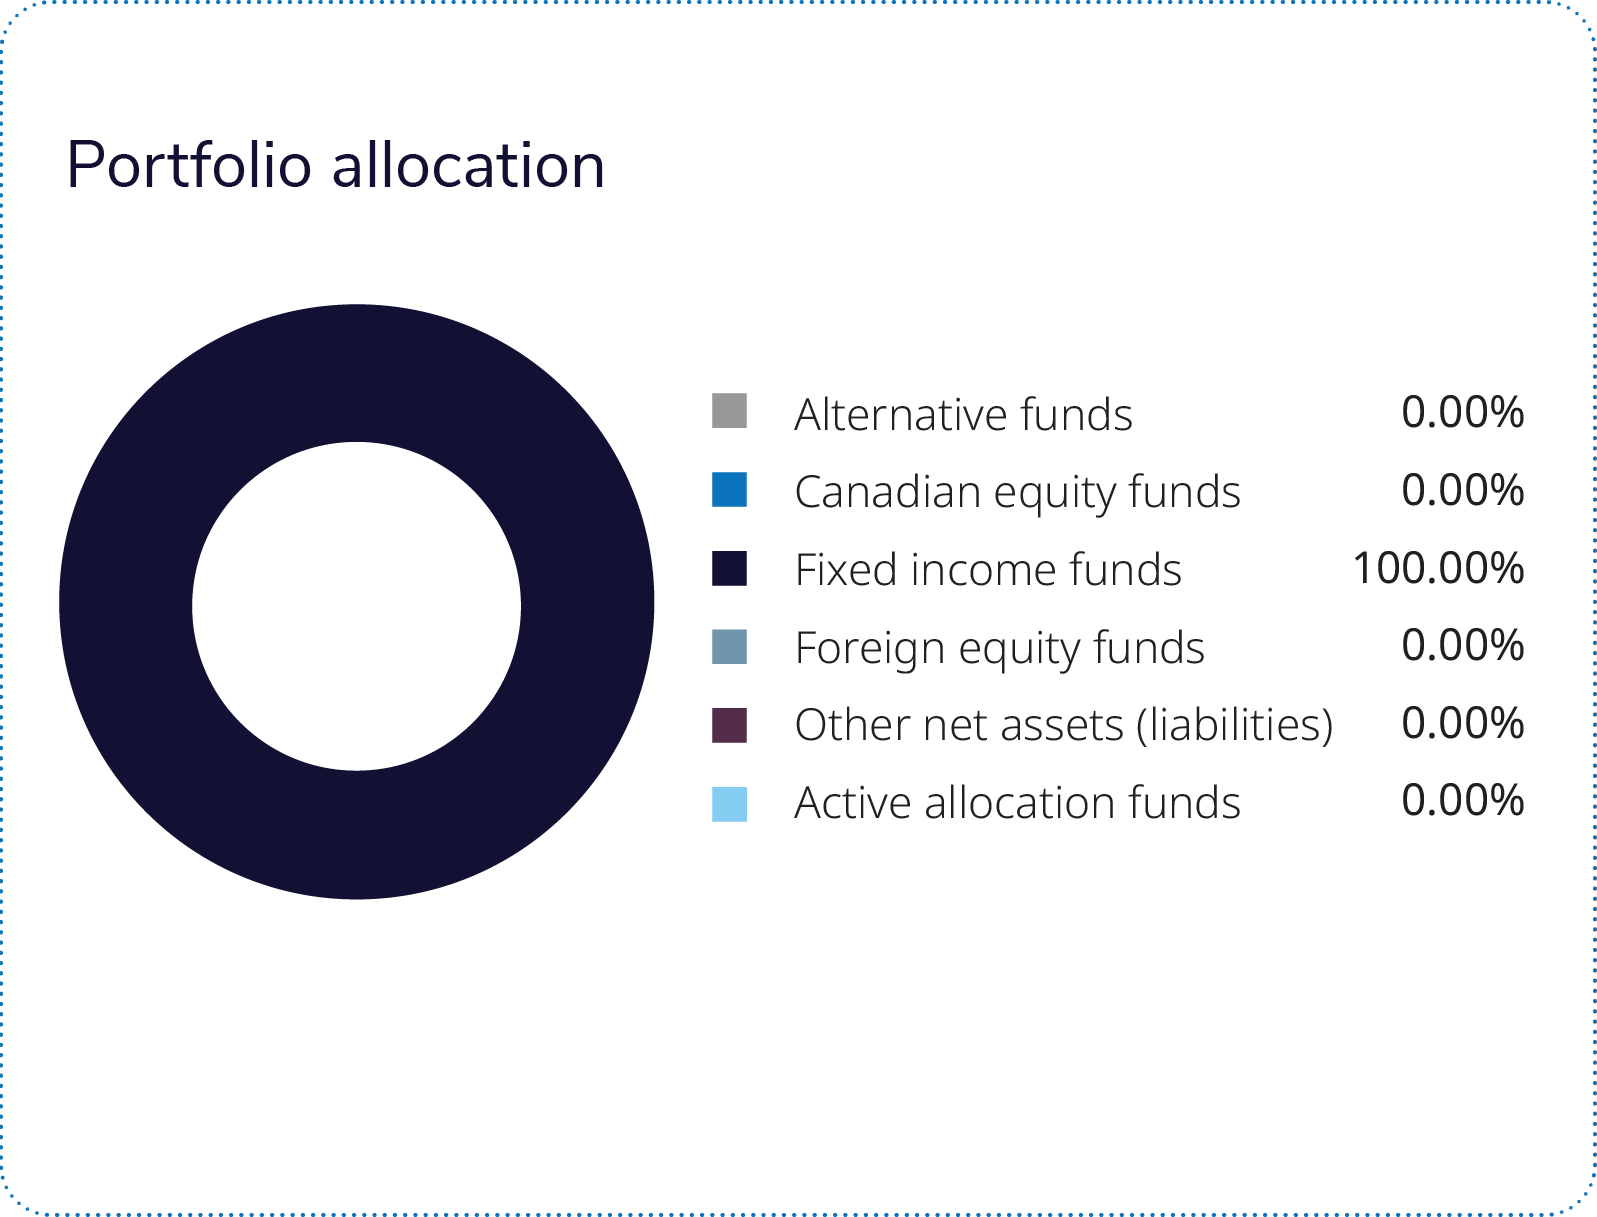 The portfolio maintained a significant overweight to corporate credit and an underweight to government bonds. Corporate exposure averaged 67% during the quarter versus 31.6% for the benchmark, ending at 65% versus 31.4%. Government exposure averaged 31.2% versus 68.4% and ended at 34.3% versus 68.6%. Average effective duration was 2.78 years, slightly shorter than the benchmark at 2.82 years.
The underweight to federal bonds was the largest contributor to relative performance. Federal bonds represented approximately 10.2% of the portfolio on average compared with 51.4% of the benchmark. Selected short-maturity financial, real estate and energy holdings contributed positively, along with bank loans and certain derivative exposures. Provincial bonds detracted, particularly Quebec, Alberta and Ontario issues, while the provincial allocation’s longer duration increased its sensitivity to higher yields.
Corporate credit positioning also detracted, led by financials, industrials and infrastructure. Canadian five-year bond futures and currency-forward hedges were additional headwinds. During the quarter, corporate exposure declined from 70.1% to 65%, while government exposure increased from 29.4% to 34.3%. The portfolio remained overweight provincial bonds and underweight federal bonds.
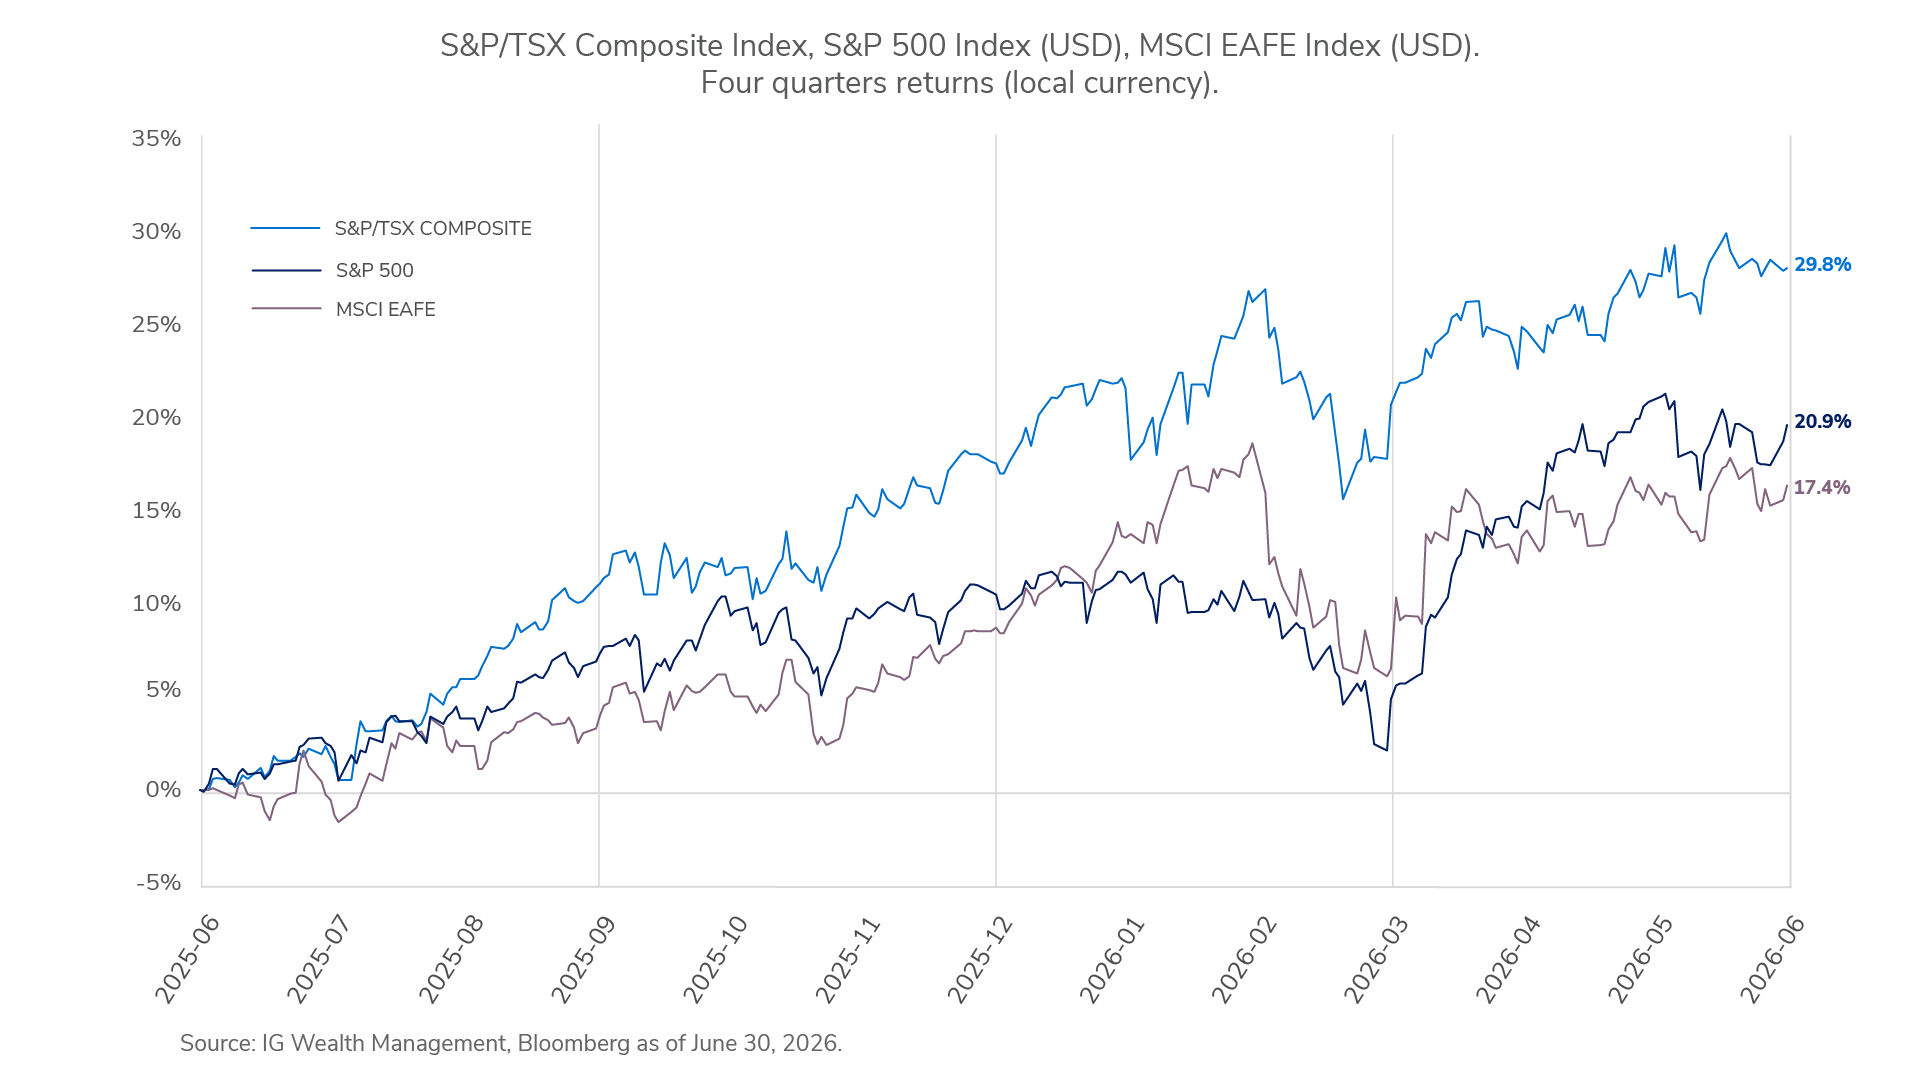
The second quarter of 2026 reinforced the resilience of financial markets. Investors faced conflict in the Middle East, commodity-price volatility, shifting interest-rate expectations and renewed inflation concerns, yet global equities continued to advance as corporate earnings and economic activity remained stronger than expected. The S&P 500 gained 14.9% in U.S.-dollar terms for the quarter, while the S&P/TSX Composite Index advanced 6.4%, supported by healthier earnings expectations and improving market breadth.
Canadian equities were led by a strong rebound in financials, as better-than-expected bank earnings, resilient credit quality and improved capital markets activity lifted sentiment. U.S. equities were supported by earnings strength rather than a simple risk-on rally, with Information Technology leading as AI infrastructure spending continued to anchor sentiment. International equities also contributed meaningfully, with emerging markets Korea and Taiwan benefitting from demand across the global technology supply chain.
The significant rise in yields across developed markets, led by the U.S., has been a defining theme of 2026. Looking ahead to the fourth quarter, the outlook for interest rates will largely depend on whether the factors driving this increase persist, moderate or reverse. Three primary factors have contributed to rising yields: persistently elevated inflation supported by higher energy prices, growing concerns surrounding government debt and fiscal deficits, and substantial corporate bond issuance driven by hyperscalers and continued investment in artificial intelligence infrastructure.
Of these factors, a reversal in energy prices appears to be the most plausible near-term catalyst for lower yields. Investment in artificial intelligence remains a strategic priority for hyperscalers, suggesting that elevated borrowing costs are unlikely to materially constrain corporate issuance. Against this backdrop, the team remains cautious about extending duration, even at current yield levels.
At the same time, higher yields have improved the income potential of corporate bonds, supporting investor demand and keeping credit spreads relatively tight despite an increasingly fragile market environment. As a result, the team continues to favour alternative opportunities to generate carry, including emerging market debt, while emphasizing relative-value opportunities rather than increasing outright duration exposure.
One area of particular interest heading into the fourth quarter is the widening yield differential between U.S. and Canadian government bonds. This spread increased by approximately 30 to 35 basis points during the third quarter across both the 10-year and 30-year maturities, creating potential relative-value opportunities that the team continues to monitor.
Commissions, fees and expenses may be associated with mutual fund investments. Read the prospectus and speak to an IG Advisor before investing. The rate of return is the historical annual compounded total return as of June 30, 2026, including changes in value and reinvestment of all dividends or distributions. It does not take into account sales, redemption, distribution, optional charges or income taxes payable by any securityholder that would have reduced returns. Mutual funds are not guaranteed, values change frequently and past performance may not be repeated. Mutual funds and investment products and services are offered through the Mutual Fund Division of IG Wealth Management Inc. (in Quebec, a firm in financial planning). And additional investment products and brokerage services are offered through the Investment Dealer, IG Wealth Management Inc. (in Quebec, a firm in financial planning), a member of the Canadian Investor Protection Fund.
This commentary may contain forward-looking information which reflects our or third-party current expectations or forecasts of future events. Forward-looking information is inherently subject to, among other things, risks, uncertainties and assumptions that could cause actual results to differ materially from those expressed herein. These risks, uncertainties and assumptions include, without limitation, general economic, political and market factors, interest and foreign exchange rates, the volatility of equity and capital markets, business competition, technological change, changes in government regulations, changes in tax laws, unexpected judicial or regulatory proceedings and catastrophic events. Please consider these and other factors carefully and do not place undue reliance on forward-looking information. The forward-looking information contained herein is current only as of June 30, 2026. There should be no expectation that such information will in all circumstances be updated, supplemented or revised whether as a result of new information, changing circumstances, future events or otherwise.
This commentary is published by IG Wealth Management. It represents the views of our Portfolio Managers and is provided as a general source of information. It is not intended to provide investment advice or as an endorsement of any investment. Some of the securities mentioned may be owned by IG Wealth Management or its mutual funds, or by portfolios managed by our external advisors. Every effort has been made to ensure that the material contained in the commentary is accurate at the time of publication, however, IG Wealth Management cannot guarantee the accuracy or the completeness of such material and accepts no responsibility for any loss arising from any use of or reliance on the information contained herein.
Trademarks, including IG Wealth Management and IG Private Wealth Management, are owned by IGM Financial Inc. and licensed to subsidiary corporations.
©2026 IGWM Inc.